First-Time Homebuyer Steps in Virginia: A Roanoke Valley Guide
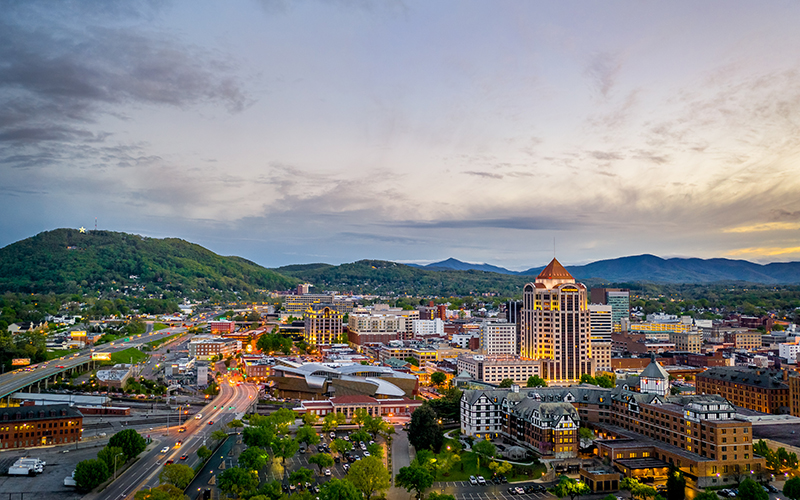
Buying your first home can feel like learning a new language. Pre-approval, escrow, recordation tax, appraisal: it is a lot. The good news is that the process is very learnable, and Virginia offers real help for first-time buyers. Here is the path I walk my Roanoke Valley clients through, from first budget to getting the keys.
Step 1: Get your finances and credit ready
Start with the basics. Pull your credit reports, check for errors and avoid opening new credit before you buy. Add up your monthly debts, your savings and what you can comfortably spend on a monthly payment. Lenders look at your credit score and debt-to-income ratio, but also decide what payment feels comfortable for you.
Step 2: Choose a loan type
You have more options than most people realize.
- FHA loan. The minimum down payment is 3.5% with a credit score of 580 or higher, and 10% for scores of 500 to 579. Many lenders set their own higher minimum score. FHA loans carry mortgage insurance. The 2026 FHA limit in most of Virginia outside high-cost areas is about $541,000 for a single-family home, which covers most Roanoke Valley purchases.
- Conventional loan. Programs allow as little as 3% down for first-time buyers, and private mortgage insurance can be removed once you build enough equity.
- VA loan. Eligible veterans and service members may buy with no down payment and no monthly mortgage insurance.
- USDA loan. Zero-down financing for eligible buyers, based on the property's location and your household income. It is not just for farm country: some addresses surprisingly close to town qualify. One of my buyers qualified for a USDA loan on a home about a mile from Northside High School. If you might qualify, it is always worth checking the eligibility map.
- Virginia Housing loans. The state housing agency offers conventional, FHA, VA and USDA loan options with special terms for eligible buyers.
Mortgage rates move constantly, and they differ by loan type, down payment and credit profile, so ask your lender for today's numbers. As an example, a $250,000 loan at 6.75% over 30 years carries a principal-and-interest payment of about $1,621 a month, before taxes and insurance. FHA and VA loans are often priced a little differently than conventional loans, so it pays to compare.
Step 3: Look for down payment help
This is the step first-time buyers skip most often. Virginia Housing offers a Down Payment Assistance Grant, generally around 2% to 2.5% of the purchase price, that does not need to be repaid. It is used with a Virginia Housing first mortgage, and income limits, program rules and homebuyer education usually apply. The Virginia Housing Plus second mortgage and closing cost assistance for VA and USDA loans are other options. For these programs, a "first-time buyer" generally means you have not owned a home in the past three years.
Programs, income limits and grant amounts change, so confirm current terms with a Virginia Housing-approved lender.
Step 4: Get pre-approved
A pre-approval letter shows sellers you are serious, and it tells you what you can actually afford. You will provide pay stubs, tax returns, bank statements and ID. Get pre-approved before you tour homes seriously, since an offer without one is rarely taken seriously. I can recommend a lender who will help you understand your buying power and which loan options fit you best.
Step 5: Find your home
This is the fun part, and it is where a local agent earns their keep. Median prices vary widely across the Valley. Redfin put the Roanoke metro's first-half 2026 median sale price at about $307,000, but a condo in Roanoke City, a ranch in Vinton and a house near Smith Mountain Lake are very different purchases. Property taxes also differ by locality, which affects your monthly payment. Make a list of must-haves and nice-to-haves, and be ready to adjust.
Step 6: Write a creative, smart offer
Making an offer is an art in its own right, and sometimes you have to get creative. Offering the most money is not always the way to win. What wins is the offer as a whole: price, seller concessions and terms, written to make the best use of your funds. Your cash on hand, your down payment, the amount you borrow and your monthly budget all shape how we build it.
Recently, I helped a buyer win in a multiple-offer situation using escalation language and creative inspection and seller-paid repair terms. For another client, I secured the home at full price, then spent several weeks negotiating during the due diligence period and won a $20,000 credit. The best transactions give both sides a win, and I structure every offer with that in mind.
Step 7: Inspect and appraise
After the seller accepts, you will typically schedule a home inspection, and your lender will order an appraisal. If the inspection turns up problems, we can negotiate repairs or credits. If the appraisal comes in low, we have options.
Step 8: Understand your Virginia closing costs
Budget for closing costs of roughly 2% to 5% of the purchase price, depending on the loan and the deal. Common buyer costs include:
- Lender fees and your loan origination charges
- Appraisal and inspection fees
- Title insurance and settlement fees
- Virginia recordation tax, which is $0.25 per $100 on the deed and another $0.25 per $100 on the deed of trust (your loan)
- Prepaid items such as homeowners insurance and tax and insurance escrows
For example, on a $250,000 purchase with a 3.5% down payment, the recordation tax is roughly $625 on the deed and about $603 on the loan. Virginia's grantor's tax is customarily paid by the seller. Who pays what can be negotiated in the contract, so I will review your estimated costs with you early.
Step 9: Close and get the keys
Closing is usually 30 to 45 days after the contract is accepted. You will do a final walk-through, review your Closing Disclosure, sign your documents and get your keys. A title company or attorney handles the settlement.
Frequently asked questions
How much do I need for a down payment?
Not 20%. FHA loans start at 3.5% down, some conventional programs at 3%, and VA and USDA loans can be zero down. Down payment assistance may cover part of it.
Who counts as a first-time homebuyer?
Generally someone who has not owned a home in the past three years, though each program defines it, and some programs waive the rule in certain areas.
Do I need a real estate agent to buy a home?
You are not required to have one, but a buyer's agent helps with pricing, negotiation, inspections and contracts, and how agent compensation works is discussed and agreed in writing up front, before we tour homes.
How long does it take to buy a home?
Plan on a few weeks to get your finances ready, anywhere from a few weeks to a few months to find the right home, and about 30 to 45 days from contract to closing.
Ready to take the first step?
I would love to help you buy your first home in Roanoke, Salem, Vinton, Bedford or around Smith Mountain Lake. Request my free buyer guide, or call or text me at 540-314-3706, and we will map out your plan together.
Leslie Epperly, REALTOR® with Real Broker, LLC. ABR, AHWD, PMN. More Than a Move.
This post is general information, not financial or legal advice. Loan terms, rates, income limits and assistance programs change often, so please confirm current details with a licensed lender and Virginia Housing.
Categories
Recent Posts